
China Resources Land (SEHK:1109) Stock Valuation After HSBC’s Top Pick Call And Margin Recovery Outlook
HSBC’s latest Asia emerging markets report has put China Resources Land (SEHK:1109) on investors’ radar after highlighting expected margin improvement and upcoming flagship launches in Shanghai and Shenzhen.
See our latest analysis for China Resources Land.
At a share price of HK$37.28, China Resources Land has seen short term momentum cool slightly with a 1 month share price return that declined 2.41%. However, the 90 day share price return of 23.94% and 1 year total shareholder return of 38.78% point to interest building over a longer horizon as investors respond to improving margin expectations and the upcoming Shanghai and Shenzhen launches.
If HSBC’s call has you thinking more broadly about where capital could go next, it may be worth scanning opportunities through the 103 top founder-led companies
With HSBC flagging margin improvement, a reported intrinsic discount of 48.53% and the stock trading about 12.08% below its consensus price target, investors may need to consider whether there is still a buying opportunity or if markets are already pricing in future growth.
Preferred P/E of 9x: Is it justified?
On a P/E of 9x and a last close of HK$37.28, China Resources Land is screening as undervalued compared to both the wider Hong Kong real estate sector and its closer peer group.
The P/E multiple compares the current share price with earnings per share and is a common way to gauge how much investors are paying for each unit of profit. For a real estate developer and landlord like China Resources Land, it gives a quick sense of how the market is weighing its earnings profile, capital intensity and sector specific risks versus the rest of the market.
Here, the stock trades on a P/E of 9x against an estimated fair P/E of 14.5x. This implies a level the market could move towards if perceptions on earnings quality and resilience shift. It also sits below the Hong Kong real estate industry average P/E of 10.1x and well below the peer average P/E of 19.7x, which is a notable gap for investors to consider when comparing listed options in the sector.
Explore the SWS fair ratio for China Resources Land
Result: Price-to-earnings of 9x (UNDERVALUED)
However, revenue that declined 2.66% and reliance on the PRC for all reported revenue mean that policy shifts or weaker sales could quickly challenge this valuation story.
Find out about the key risks to this China Resources Land narrative.
Another view from the SWS DCF model
The P/E of 9x paints one picture, but the SWS DCF model offers a different one. On this view, China Resources Land at HK$37.28 is trading below an estimated fair value of HK$72.43, suggesting the market price is well under the model’s long term cash flow estimate. That kind of gap raises a simple question: which signal do you trust more, current earnings or future cash flows?
For a closer look at how this cash flow view is built and what it assumes about the future, Look into how the SWS DCF model arrives at its fair value.
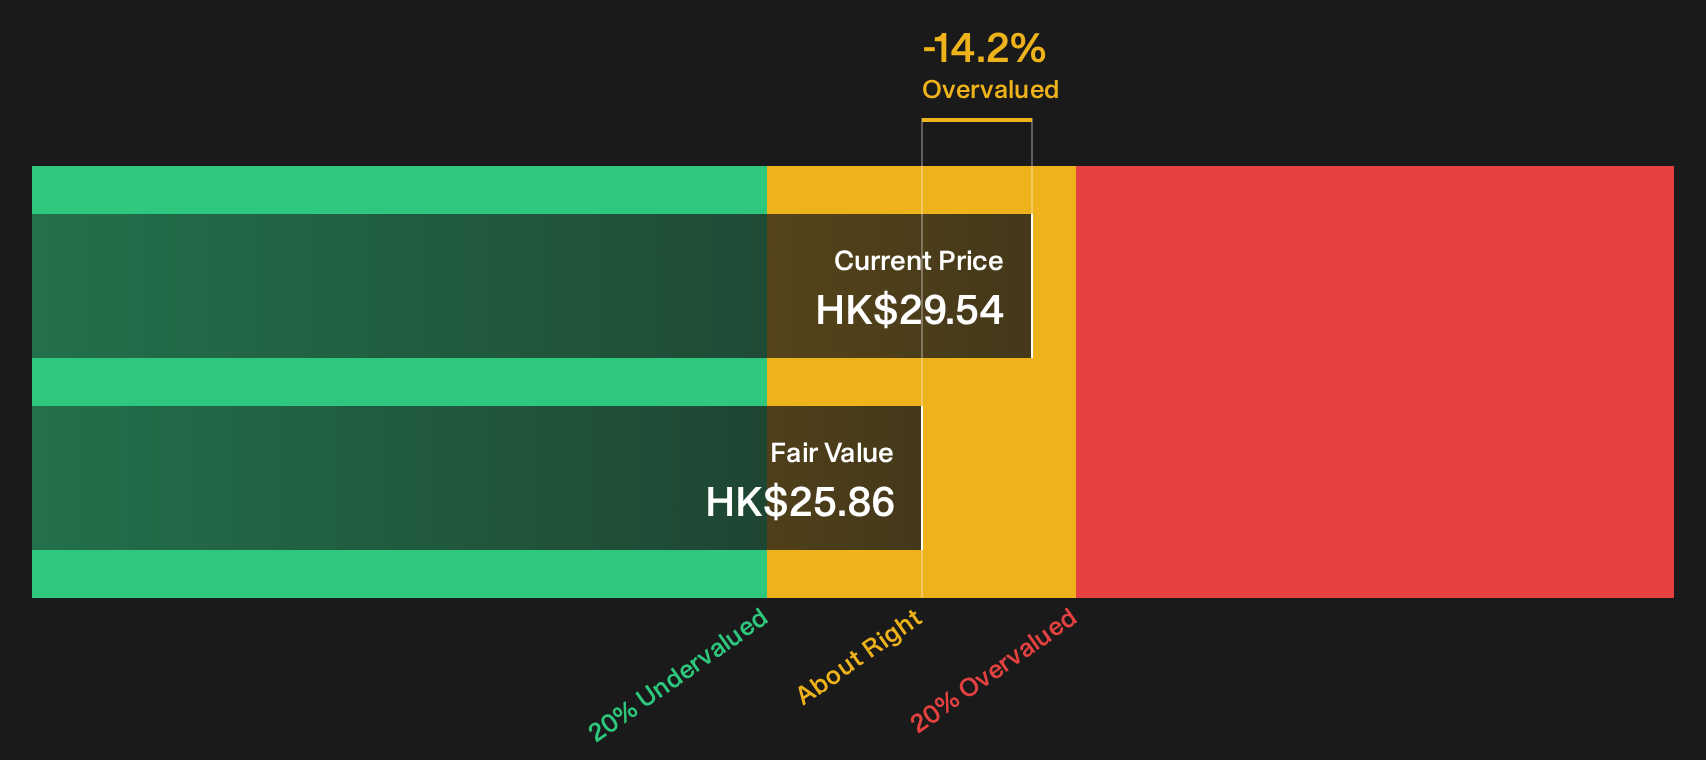
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Land for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear opportunity, either way it makes sense to move quickly. Review the full picture for yourself and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas?
If you are serious about putting your capital to work, do not stop at a single stock. Use targeted screens to surface ideas that match your goals fast.
- Zero in on quality at a discount by scanning 192 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them.
- Strengthen the defensive side of your portfolio by checking out 279 resilient stocks with low risk scores that score well on resilience and financial stability.
- Add yield potential to your watchlist by reviewing 484 dividend fortresses that combine higher income with business models focused on consistent payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English