
Assessing China Resources Land (SEHK:1109) Valuation After Mixed March Sales And Rental Trends
Mixed March Sales and Rental Trends Put China Resources Land in Focus
China Resources Land (SEHK:1109) released unaudited March and past 3 months 2026 sales data, showing weaker contracted sales and gross floor area, alongside higher recurring revenue and rental income from its investment property rental business.
See our latest analysis for China Resources Land.
Despite softer contracted sales in March, investors have recently priced in some optimism, with the latest share price at HK$31.92 and a year to date share price return of 15.15% alongside a 1 year total shareholder return of 22.86%. This suggests that momentum has been building over recent months.
If mixed property sales and rental trends have your attention, it can be useful to see what else is moving in related areas of the market by checking out 33 power grid technology and infrastructure stocks
So with sales under pressure but rental income and a 22.86% 1 year total return already on the table, should you see China Resources Land as still trading at a discount, or is the market already pricing in expectations for the company?
Price-to-Earnings of 7.8x: Is it justified?
At a last close of HK$31.92, China Resources Land is trading on a P/E of 7.8x, which screens as good value relative to both peers and the wider Hong Kong Real Estate industry.
The P/E multiple compares the current share price with earnings per share, so a lower P/E can suggest the market is attaching a lower price tag to each unit of earnings. For a large property group with ongoing earnings and a mix of development and rental income, this ratio is often a quick way to see how the market is treating those profits.
Here, the company is described as good value versus its peer average P/E of 20.6x and the Hong Kong Real Estate industry average of 10.6x, and also against an estimated fair P/E of 14.2x. That is a sizeable gap, which implies the current multiple is well below the level indicated by that fair ratio framework.
Explore the SWS fair ratio for China Resources Land
Result: Price-to-Earnings of 7.8x (UNDERVALUED)
However, softer annual revenue growth of 2.8% and weaker contracted sales in March could challenge the idea that the current P/E discount will close.
Find out about the key risks to this China Resources Land narrative.
Another Angle: SWS DCF Points to Deeper Value
While the 7.8x P/E already looks low against peers, the SWS DCF model goes further and puts fair value at HK$72.44 versus the current HK$31.92. That gap suggests the market might be pricing China Resources Land below its estimated future cash flow potential. What factors could close or widen that gap next?
Look into how the SWS DCF model arrives at its fair value.
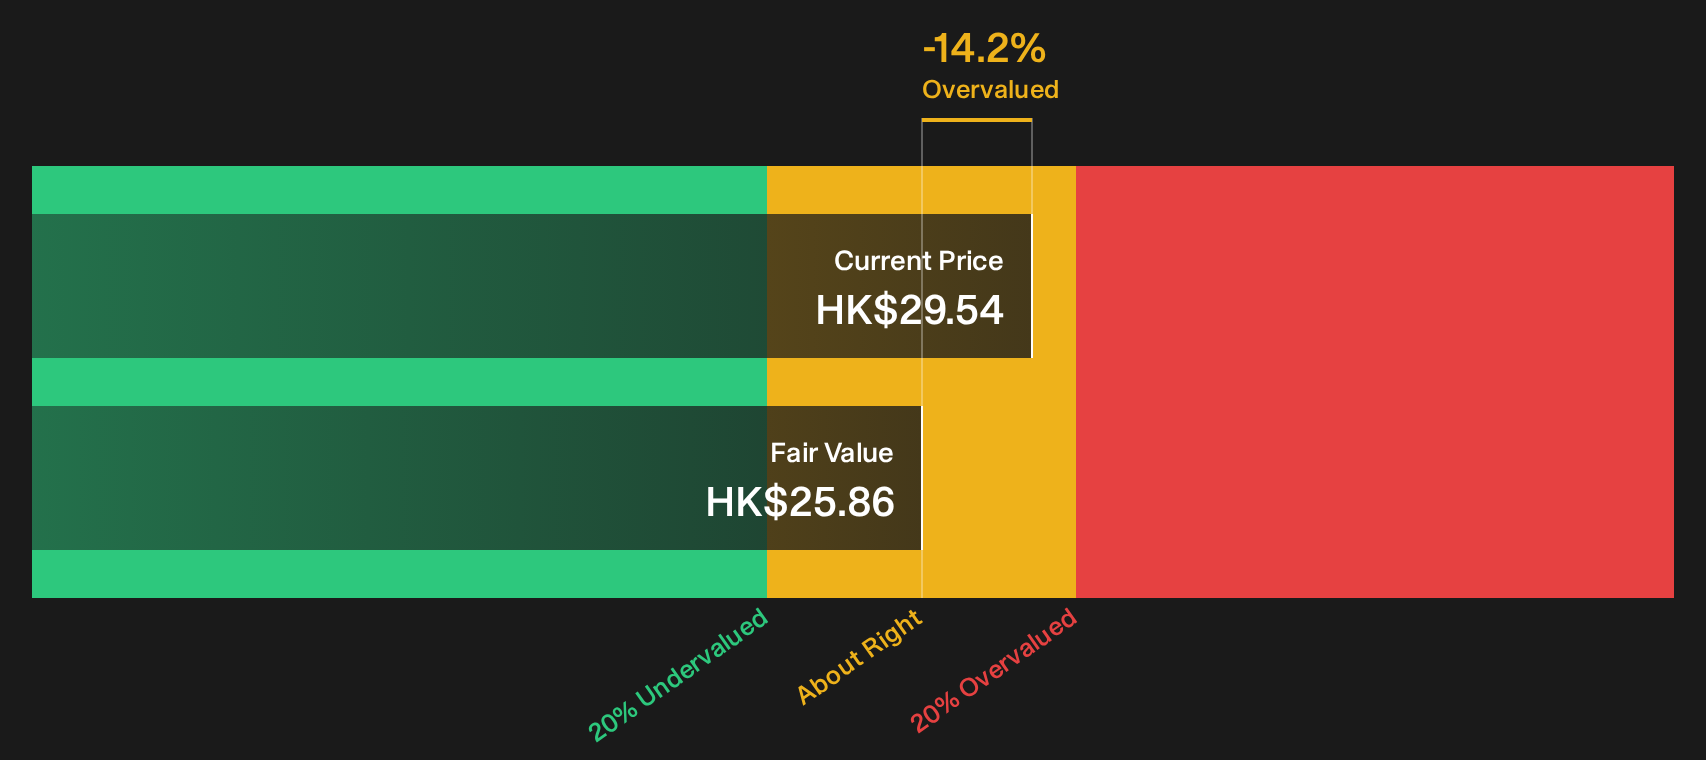
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Land for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 234 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Given the mixed signals so far, it makes sense to look at the full picture yourself and decide how comfortable you are with both the upside and the risks. Then weigh those factors using our 5 key rewards and 1 important warning sign
Ready for more investment ideas?
If China Resources Land has sparked your interest, do not stop here. A few focused stock lists can quickly surface ideas that better match your goals.
- Target value opportunities by scanning companies that currently appear mispriced on quality and fundamentals with the 234 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses screened for stronger balance sheets and core metrics using the solid balance sheet and fundamentals stocks screener (385 results).
- Hunt for lesser known potential by reviewing companies picked out as a screener containing 567 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English